
 Facebook
 X
 Pinterest
 Copy Link
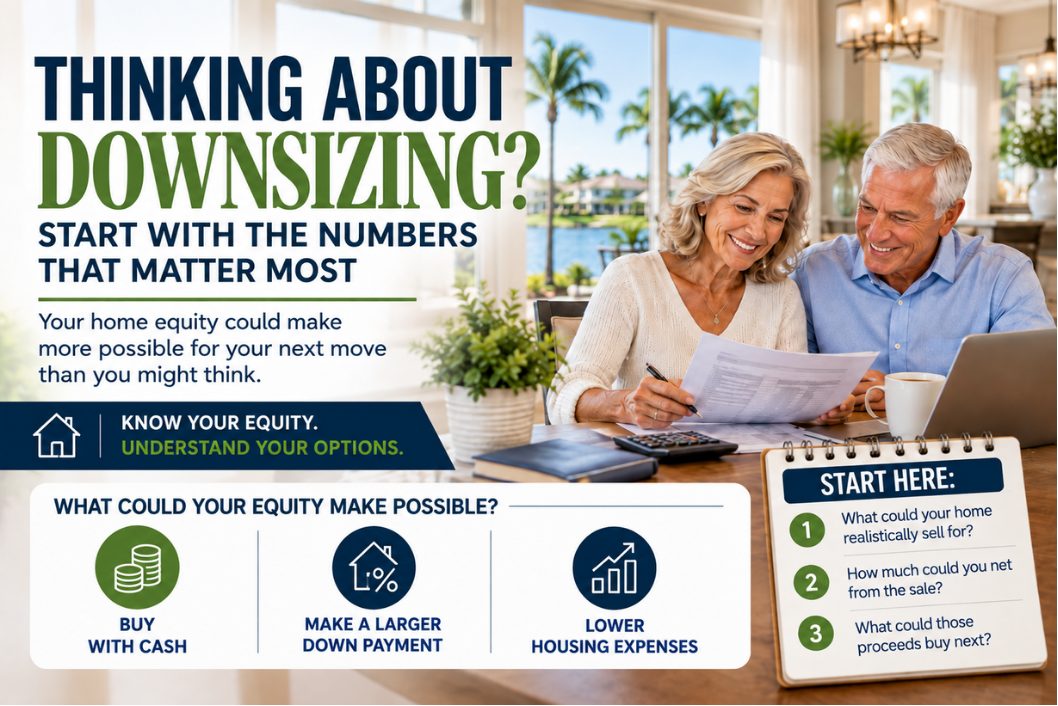
If you have lived in your Miramar or Pembroke Pines home for 15, 20, or even 25 years, you may have thought about downsizing your home.
But before you start looking at smaller homes, there is probably a much bigger question on your mind:
If I sell my house, how much money will I actually walk away with, and what will that allow me to buy next?
For many longtime homeowners, that is the question that determines whether downsizing makes financial sense.
You may not simply want a smaller house. Instead, you may want a smaller monthly housing expense.
Perhaps you would like to buy your next home with cash. Or you might make a large enough down payment that you only need a small mortgage. You may also want lower insurance costs, less maintenance, a smaller electric bill, or fewer expensive repairs ahead.
Fortunately, you do not have to make a decision before you know whether any of this is possible.
You can start with the numbers.
How Much Would I Net If I Sold My Home?
Your home’s estimated selling price and the amount you would actually receive after the sale are two different numbers.
What you really want to know is your estimated net proceeds.
To calculate that, start with the likely market value of your home. Next, consider your remaining mortgage balance, if you have one, along with estimated selling and closing expenses.
The result gives you a much better idea of the equity that could potentially be available for your next move.
For longtime homeowners in Miramar, Pembroke Pines, and other Broward County communities, that number can sometimes be surprising.
For example, you may have purchased your home many years ago at a considerably lower price. Over time, you may also have paid down most or all of your mortgage.
As a result, that accumulated equity could become the financial bridge between the home you own today and the lifestyle you want next.
What Could I Buy With the Money From My Sale?
This is where the downsizing conversation becomes much more interesting.
Suppose you determine that you could sell your current home and have substantial proceeds available after the sale.
Naturally, the next question becomes:
“What could that money buy?”
Instead of beginning your search based only on today’s mortgage rates or the asking prices you see online, consider several possibilities.
Could you purchase your next property entirely with cash?
Perhaps you could put enough money down to have a very small mortgage. Another possibility is purchasing a newer home that may require fewer major repairs.
Depending on your needs, you might also consider a villa, townhouse, condo, 55+ community, or smaller single-family home that better fits the way you live today.
These are very different scenarios, and each one can affect your finances differently. Therefore, it helps to understand both sides of the equation before deciding whether to stay or move.
Could Downsizing Lower My Monthly Expenses?
This may be the most important question of all.
A successful downsize is not necessarily about moving from 3,000 square feet to 1,800 square feet. Instead, it may be about creating a home and a monthly budget that work better for the next chapter of your life.
Start by considering what you currently spend on your home each year.
Your expenses may include property taxes, homeowners insurance, electricity, water, landscaping, pool service, HOA fees, routine maintenance, and repairs.
In addition, larger expenses come along periodically: a roof, air conditioning system, exterior painting, plumbing, appliances, pool equipment, or major landscaping.
A larger home can be wonderful when you need the space. However, once bedrooms are rarely used, children have moved out, or maintaining the property becomes less appealing, the cost of keeping that extra space may deserve a second look.
But Does a Smaller Home Always Cost Less?
No, and this is important.
A smaller home does not automatically mean lower expenses.
For instance, a condominium may have a substantial monthly association fee. A newer community may have HOA fees or additional assessments. Property taxes can also change when you purchase another property. Meanwhile, insurance costs can vary considerably depending on the type, age, and location of the home.
That is why the right question is not:
“Can I afford to buy a smaller house?”
Instead, ask:
“What will my total housing expenses look like after I move?”
Compare the entire picture. Your potential mortgage payment, property taxes, insurance, HOA or condo fees, utilities, maintenance, and anticipated repairs should all be part of the conversation.
Would I Need a Mortgage at All?
For some longtime homeowners, this is where accumulated home equity can make downsizing especially worth exploring.
If your current home has appreciated over many years and your mortgage balance is low, you may discover that you have enough equity to purchase another property with cash.
For others, however, the goal may not be eliminating a mortgage completely.
You might sell a larger home and use a substantial portion of the proceeds toward your next purchase. As a result, instead of financing most of the new property, you may only need a relatively small mortgage.
That could potentially create a very different monthly financial picture.
Most importantly, do not assume that today’s mortgage rates automatically make moving impractical. First, determine how much you would actually need to borrow.
Should I Spend Money Updating My Current Home Before Selling?
This is another financial question that deserves attention before you make major improvements.
Maybe your kitchen is dated. Perhaps your roof is getting older or a bathroom needs updating. You may also know there are projects you could complete, but you are not sure you want to invest another $30,000, $50,000, or more into a home you may sell in the next few years.
Before spending that money, find out what buyers in your local market are actually expecting.
Some improvements may help your home compete and increase its appeal. Others, however, may not provide enough return to justify the cost.
Fortunately, you may also have options for preparing the property strategically without completing every improvement you have been considering.
Start Your Downsizing Decision With Three Numbers
You do not need to start by packing boxes. Nor do you need to begin by putting your home on the market.
Instead, start with three numbers:
- What could my current home realistically sell for?
- Approximately how much would I net from the sale?
- What could I realistically buy with those proceeds?
Then take it one step further.
Compare what you spend to own your home today with what you might spend after moving.
At that point, downsizing stops being a vague idea and becomes something you can actually evaluate.
FAQs About Downsizing and Home Equity
How much will I net if I sell my home?
Your net proceeds are different from your home’s selling price.
Start with your expected sales price. Then subtract your remaining mortgage balance, estimated closing costs, and selling expenses.
This gives you a better estimate of how much money may be available after the sale. From there, you can see how much equity you may have for your next home.
Can I use my home equity to buy my next home with cash?
Possibly. Longtime homeowners who have built substantial equity may have enough proceeds to purchase a smaller or less expensive home with cash.
Others may be able to make a large down payment and only need a small mortgage.
The first step is to find out what your current home could realistically sell for. Then estimate how much you may net from the sale.
Does downsizing really save money?
It can, but a smaller home does not automatically mean lower expenses.
Look beyond the purchase price. Compare your mortgage payment, property taxes, homeowners insurance, HOA or condo fees, and utilities. Also consider maintenance and future repairs.
The goal is to understand your total housing costs. Then you can decide whether downsizing could provide the financial and lifestyle benefits you want.
Should I sell my current home before buying my next one?
It depends on your finances, available equity, and the type of property you want to buy.
Some homeowners need the proceeds from their current home to fund their next purchase. Others may have enough financial flexibility to buy first.
Start by understanding your home’s value and estimated net proceeds. That information can help you determine which approach may work best for you.
How do I know if downsizing makes financial sense for me?
Start with three numbers:
1. What could my current home realistically sell for?
2. Approximately how much could I net from the sale?
3. What is the type of home I want next likely to cost?
Next, compare your current housing expenses with what you may spend after moving.
You may find that downsizing could reduce your mortgage or lower certain ongoing expenses. In some cases, your equity may even make it possible to purchase your next home with cash.
Where should I start if I am thinking about downsizing in Miramar or Pembroke Pines?
You do not have to start by packing, making repairs, or searching for another home.
Instead, start by understanding your current home’s market value. Then estimate how much you might net from the sale.
Once you know how much equity may be available, you can explore what those proceeds could buy. From there, you can decide whether moving makes sense for your financial goals and next chapter.
Final Thoughts
After running the numbers, you may decide to stay exactly where you are.
Alternatively, you may discover that downsizing makes sense, but you would rather wait another year or two.
You could also realize that the equity you have spent decades building may allow you to buy your next home with cash, substantially reduce your mortgage, lower your ongoing expenses, or simply give you greater financial flexibility.
There is no single right answer.
The goal is to understand your options before you make the decision.
For more than two decades, Sharon Flood of Coldwell Banker Realty has helped homeowners throughout Miramar, Pembroke Pines, and Broward County understand their home’s value, prepare strategically for the market, and protect the equity they have worked so hard to build.
If you have been thinking about downsizing, you do not have to figure everything out at once.
Instead, start by finding out what your home could sell for, what you might net from the sale, and what that money could make possible for your next move.
Call Sharon Flood at 954-650-2676 to schedule a no-pressure downsizing and home equity conversation.
